Brazil is Latin America's largest economy, with 123 million online shoppers recorded in 2024 and a projected annual growth rate of 10.14% through 2029. The payment landscape is defined by Pix, a central-bank-operated instant transfer system that became the dominant checkout method within four years of its 2020 launch. Digital wallet penetration reaches 85% of the population — yet card payments remain deeply embedded, making Brazil a market where three distinct rails must all be supported.
Quick facts: Brazil
Country | Brazil |
|---|---|
Population | 213.4 million |
GDP (USD) | $2,280 billion |
Currency | Brazilian Real (BRL) |
e-Commerce users (2024) | 123 million |
Digital wallet penetration | 85% of population |
What payment methods dominate Brazil's e-Commerce?
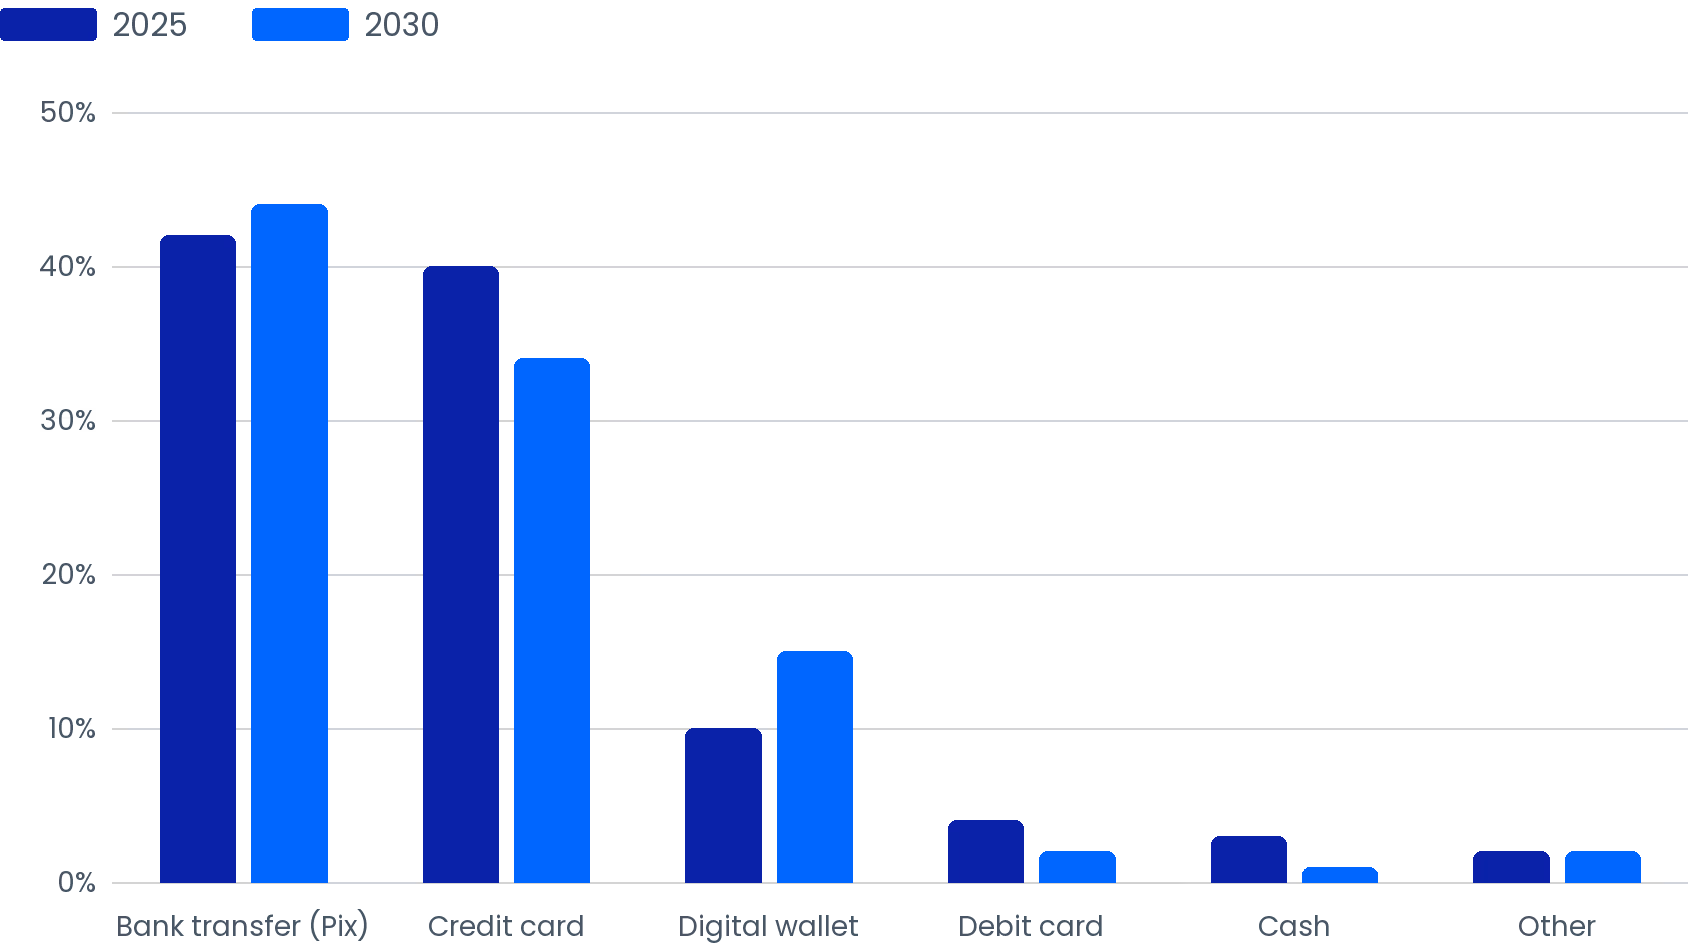
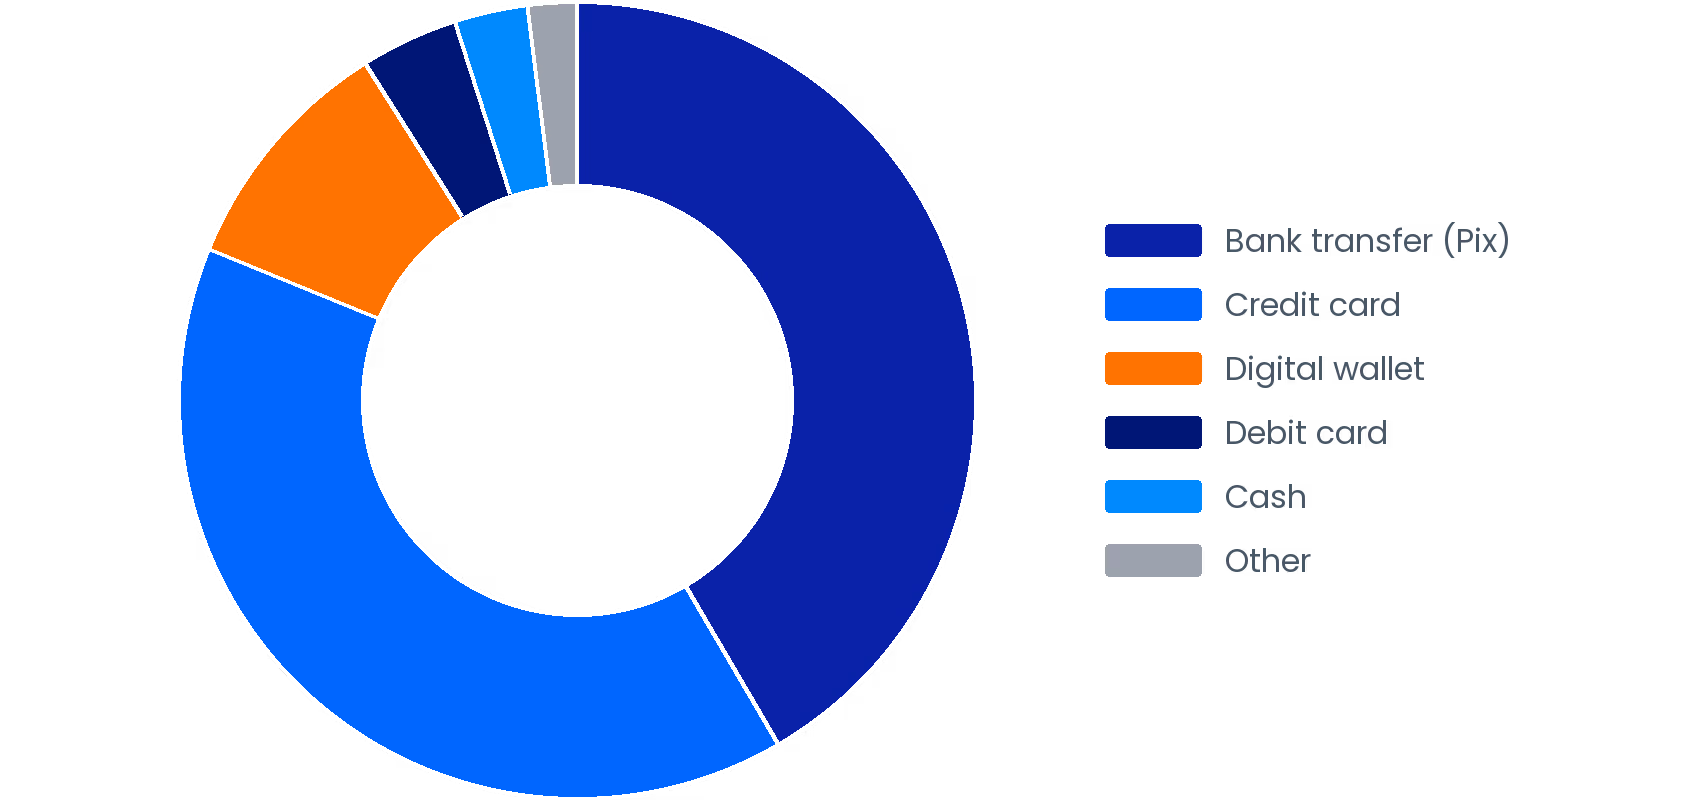
Bank transfers lead at 42% of online transactions, followed by credit cards at 40%. Pix is the main local option within the bank-transfer category. Together, bank transfers and credit cards account for approximately 82% of Brazilian online transaction volume.
- Bank transfers — 42%. Pix is the dominant local option, supporting payments around the clock. The category is projected to grow to 44% by 2030.
- Credit card — 40%. Brazil's credit card market is the most developed in Latin America. Mastercard and Visa together account for 80% of card payments; local brand Elo holds meaningful share. Brazilian consumers frequently pay in interest-free installments (parcelamento) of 3–12x — merchants can use the payment method quadrant framework to decide whether to position installment credit or Pix as the primary checkout slot for their product category.
- Digital wallet — 10%. Despite 85% population-level wallet penetration, the online shopping wallet share sits at a stable 10% — Brazilians use wallets extensively for non-payment functions beyond checkout. PayPal commands 24% of the wallet segment; Mercado Pago and PicPay hold significant local-market share.
- Debit card — 4%. Small but steady. Visa and Mastercard dominate.
- Cash — 3%. Typically fulfilled via offline payment slips at bank branches or convenience stores. Projected to decline to 1% by 2030.
Brazil 2025 payment method share
How Pix, credit cards, and wallets work for merchants in Brazil
Bank transfers and credit cards together cover 82% of Brazilian online transactions, making both important parts of a localized checkout.
Payment method | Key platforms | Approx. share | What merchants should know |
|---|---|---|---|
Bank Transfers | Pix, participating Brazilian financial institutions | ~42% | Pix returns a payment result in real time. Antom's Pix flow supports full and partial refunds, while card-style chargebacks are not listed for this method. |
Credit Card | Mastercard, Visa, Elo | ~40% | Brazilian consumers frequently pay in interest-free installments (parcelamento) of 3–12x; merchants who do not offer installment options lose a material share of higher-ticket orders. |
Digital Wallet | PayPal, Google Pay, Mercado Pago, PicPay | ~10% | Mercado Pago and PicPay operate as closed-loop ecosystems — dispute resolution timelines differ from international card scheme rules. |
Debit Card | Visa, Mastercard | ~4% | Acceptance and authentication outcomes vary by issuer and transaction. |
Cash (offline slip) | Bank branches, convenience stores | ~3% | Hold the order until payment confirmation arrives. |
How to handle failed payments in Brazil
Card authorization outcomes vary by issuer, transaction, authentication, and payment setup. If a card payment fails, merchants can present Pix or another available method for the buyer to select and complete. Pix requires a separate buyer action, such as scanning a QR code or copying a payment code; it is not an automatic background reroute. The failed payments guide covers recovery messaging and alternative-payment design.
Brazil payment method share: 2025 vs 2030 projection