Japan is the world's fourth-largest economy by GDP, with an e-Commerce market growing at a 9.23% CAGR (Compound Annual Growth Rate) and digital payment transaction volume projected to break $447.5 billion in 2025. Credit card adoption stands at 76%, creating a card-dominant online payment environment. Digital wallets are also growing rapidly.
Japan at a glance
Country | Japan |
|---|---|
Population | 123.0 million |
GDP (USD) | $4,280.0 billion |
Currency | Japanese Yen (JPY) |
Digital payment adoption | 73.12% (90.65 million users, 2025) |
e-Commerce CAGR | 9.23% |
Which payment methods do Japanese buyers use most?
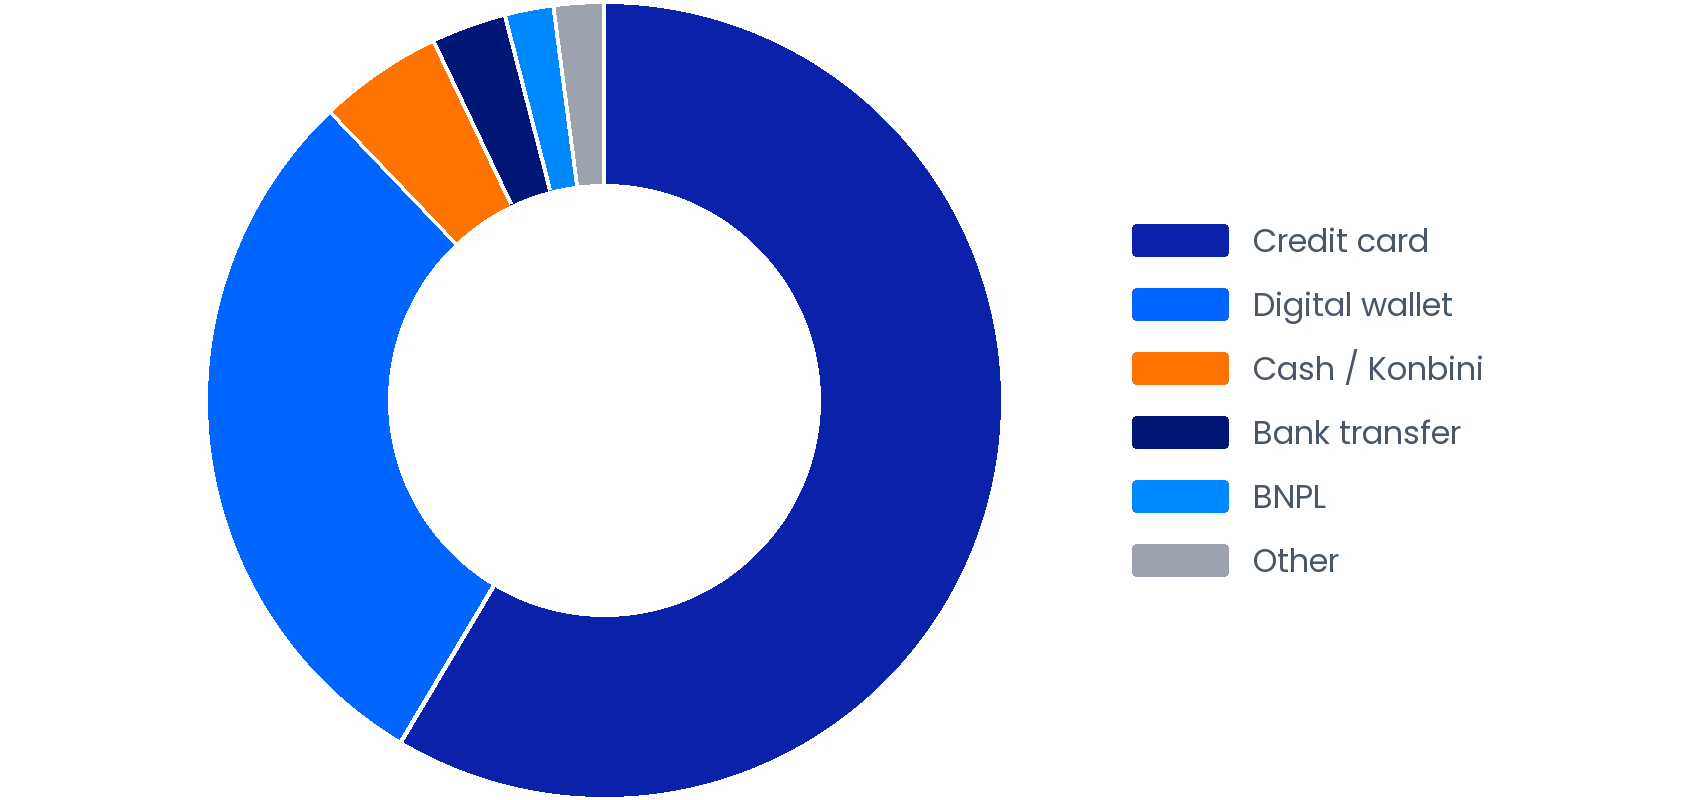
Credit cards hold 58% of Japan's e-Commerce market in 2025, with digital wallets at 29%. Together they cover 87% of online transaction value. Japan's 2025 payment breakdown:
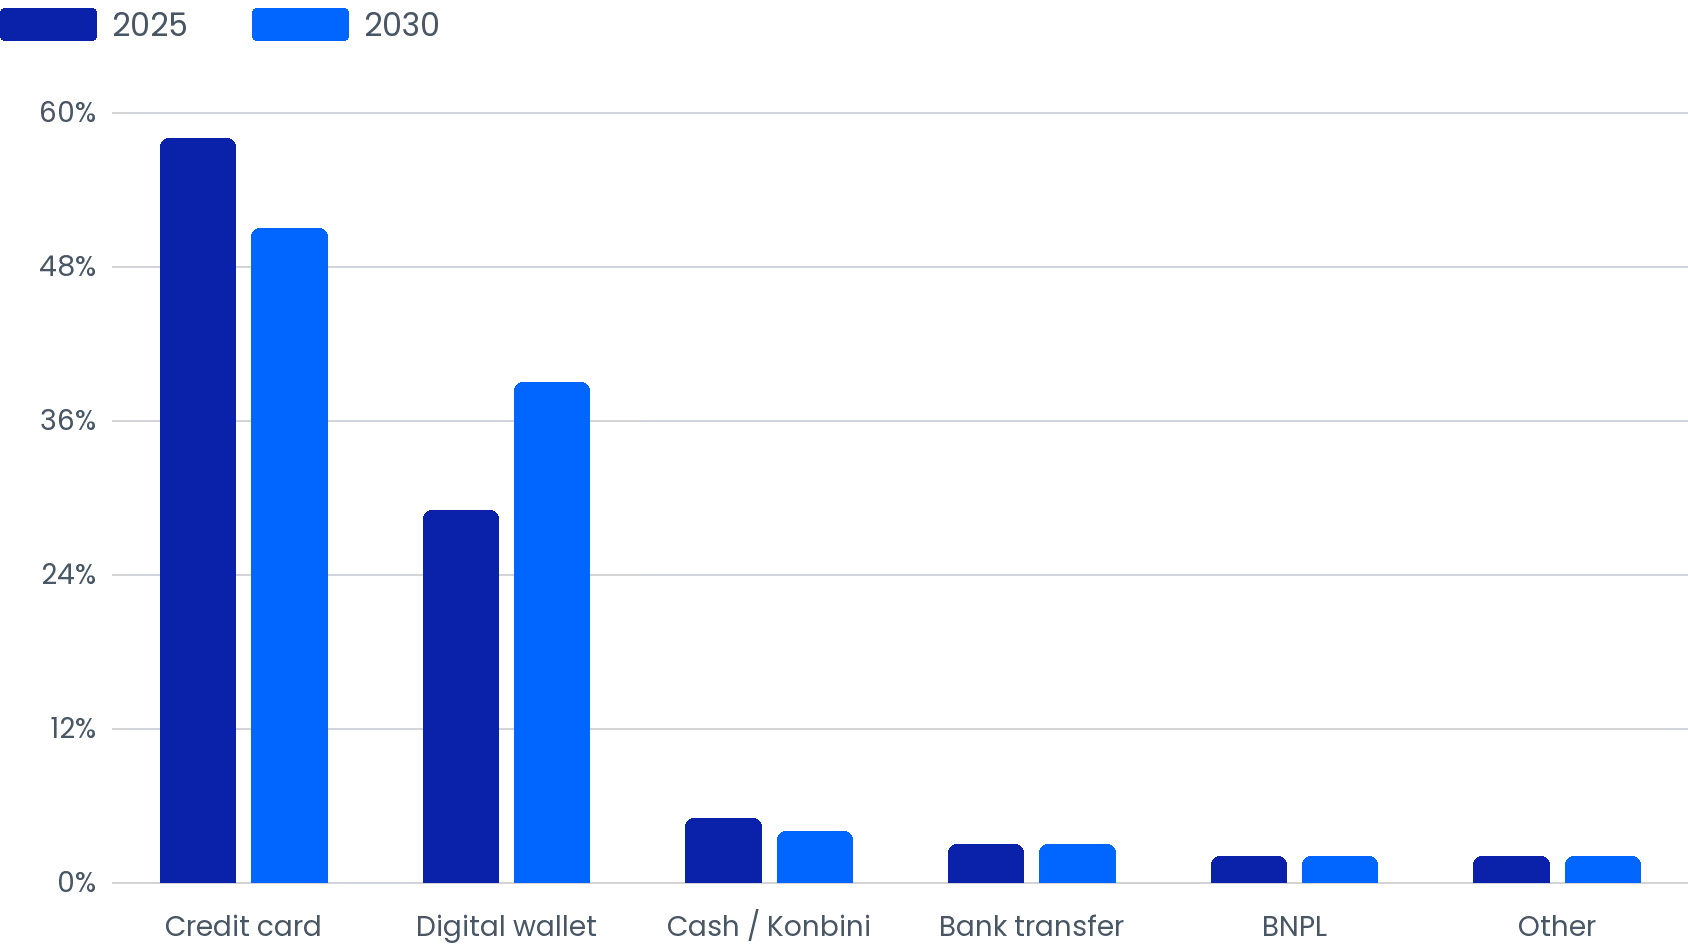
- Credit cards (~58%). JCB, Visa, and Mastercard dominate the acquiring layer. Share is projected to ease to 51% by 2030 as wallets absorb volume, but cards remain the single largest category through the decade.
- Digital wallets (~29%). PayPay, Rakuten Pay, and au PAY are prominent domestic brands. The category is projected to reach 39% by 2030.
- Cash (~5%). Konbini is an important option in this category: the buyer generates a reference code at checkout and pays at a participating convenience store within a configurable window.
- Bank transfer (~3%). Pay-easy is Japan's primary bank transfer service, supporting payments via online banking or ATM. Serves consumers who prefer not to use cards online, particularly for high-value purchases.
- BNPL (~2%). Japan's mature credit card installment culture limits the incremental appeal of standalone BNPL (Buy Now, Pay Later) products; share is projected to remain flat through 2030.
Japan 2025 e-Commerce payment method share
How credit cards, digital wallets, and Konbini work for merchants in Japan
Japan's payment environment combines high card usage with growing domestic wallets and cash-based Konbini payments. JCB acceptance requires explicit confirmation from the acquirer or payment provider. For wider card-acceptance and decline-recovery considerations, see the failed payments guide.
Payment method | Key platforms | Approx. share | What merchants should know |
|---|---|---|---|
Credit Card | JCB, Visa, Mastercard | ~58% | Verify that your provider explicitly supports JCB as well as Visa and Mastercard. |
Digital Wallet | PayPay, Rakuten Pay, au PAY | ~29% | Confirm each wallet's availability and settlement terms with your provider. |
Cash / Konbini | 7-Eleven, Lawson, FamilyMart | ~5% cash category | The payment window is provider-configurable. Confirm payment before fulfillment. |
Bank Transfer | Pay-easy | ~3% | Payments via ATM or online banking; the reference expires within a set period — confirm expiry configuration with your gateway before enabling. |
BNPL | — | ~2% | Japan's credit card installment culture limits standalone BNPL adoption; share projected to stay flat through 2030. |
How Japan's payment mix will shift by 2030
Digital wallets are the standout growth category, rising from 29% to 39% by 2030. Credit card share is projected to move from 58% to 51%, while cards remain the largest category. The payment method quadrant framework can help merchants balance the leading category with faster-growing alternatives.
Japan payment method share: 2025 vs 2030 projection