Bank transfer and digital wallets together account for 61% of Malaysian online transactions. The number of digital payment users will grow 35.45% between 2024 and 2028, reaching 31 million — nearly 90% of the country's 34.2 million population (Statista). Malaysia's defining characteristic is its dual-rail architecture: FPX (Financial Process Exchange), a bank-direct transfer network, runs parallel to a maturing e-wallet ecosystem anchored by Touch 'n Go.
Malaysia at a glance
Country | Malaysia |
|---|---|
Population | 34.2 million |
GDP (USD) | $437.0 billion |
Currency | Malaysian Ringgit (MYR) |
Dominant payment combination | Bank transfer + digital wallets: 61% combined share (Worldpay 2025) |
Digital payment users by 2028 | 31 million (+35.45% growth from 2024; Statista) |
Which payment methods do Malaysian buyers use most?
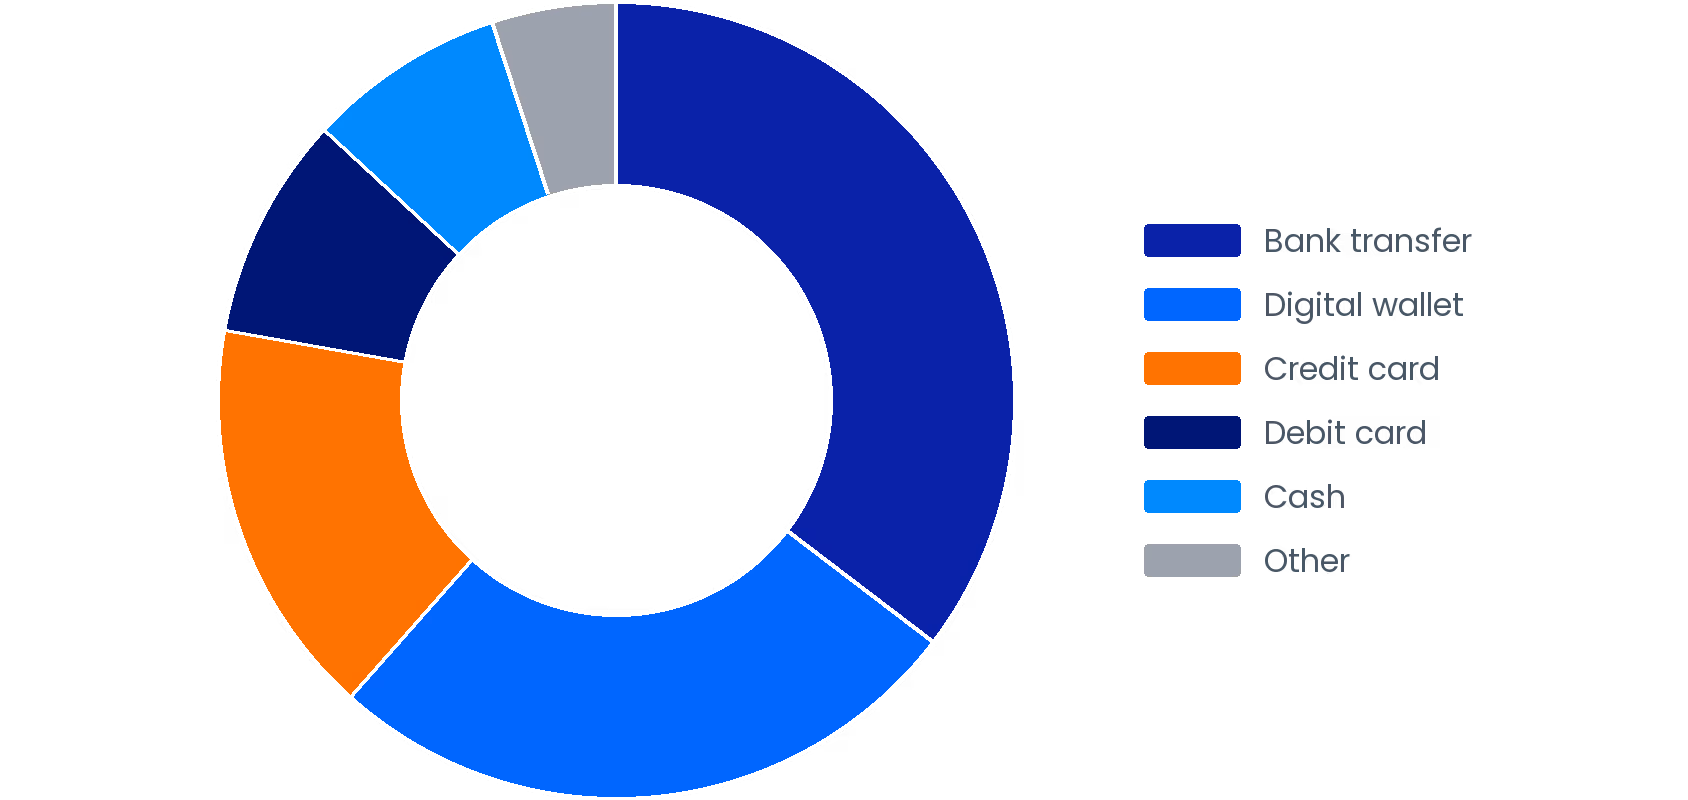
Bank transfer holds 35% of Malaysian online transactions, digital wallets 26%, and credit cards 16%. Together the top three rails cover 77% of the market. Malaysian consumers in 2025 split payments across five categories:
- Bank transfer — 35%. FPX connects buyers directly to their bank accounts, bypassing card networks entirely. DuitNow QR, Malaysia's national QR standard, has 2.6 million registered acceptance points and supports cross-border interoperability.
- Digital wallets — 26%. Touch 'n Go eWallet leads. Boost, GrabPay, and ShopeePay hold meaningful share among younger consumers. International wallets (Apple Pay, Google Pay, PayPal) have materially lower adoption than in regional peers.
- Credit card — 16%. Visa and Mastercard dominate. Share is declining as consumers migrate to mobile payment endpoints.
- Debit card — 9%. Contracting faster than credit, as FPX bank transfers serve the same account-direct function with lower friction.
- Cash — 8%. Present in COD (Cash on Delivery) models for certain product categories; compressing as digital infrastructure matures.
Malaysia 2025 e-Commerce payment method share
How FPX, wallets, and cards work for merchants in Malaysia
Malaysia's payment methods span bank transfers, digital wallets, cards, and cash. The table below outlines the main platforms and the practical differences merchants should consider when configuring checkout.
FPX redirects buyers to their bank to authorize an online transfer. Antom's FPX documentation lists full and partial refunds as supported, while card-style chargeback or dispute support is not listed for this payment method.
Payment method | Key platforms | Approx. share | What merchants should know |
|---|---|---|---|
Bank transfer | FPX, DuitNow QR | ~35% | FPX uses a bank-authorization flow. Full and partial refunds are supported through Antom. |
Digital wallet | Touch 'n Go, Boost, GrabPay, ShopeePay | ~26% | Touch 'n Go allows eligible visitors from selected countries and regions to register, subject to its account requirements. |
Credit card | Visa, Mastercard | ~16% | Cross-border authorization rates lower than Singapore or Hong Kong; configure FPX as a fallback for high-value orders. |
Debit card | Visa Debit, Mastercard Debit | ~9% | A card-based option for buyers who prefer to pay directly from their bank balance. |
Cash / COD | — | ~8% | Requires a local logistics partner; cross-border merchants without Malaysian warehouse operations cannot offer COD at launch. |
How Malaysia's payment mix shifts toward 2030
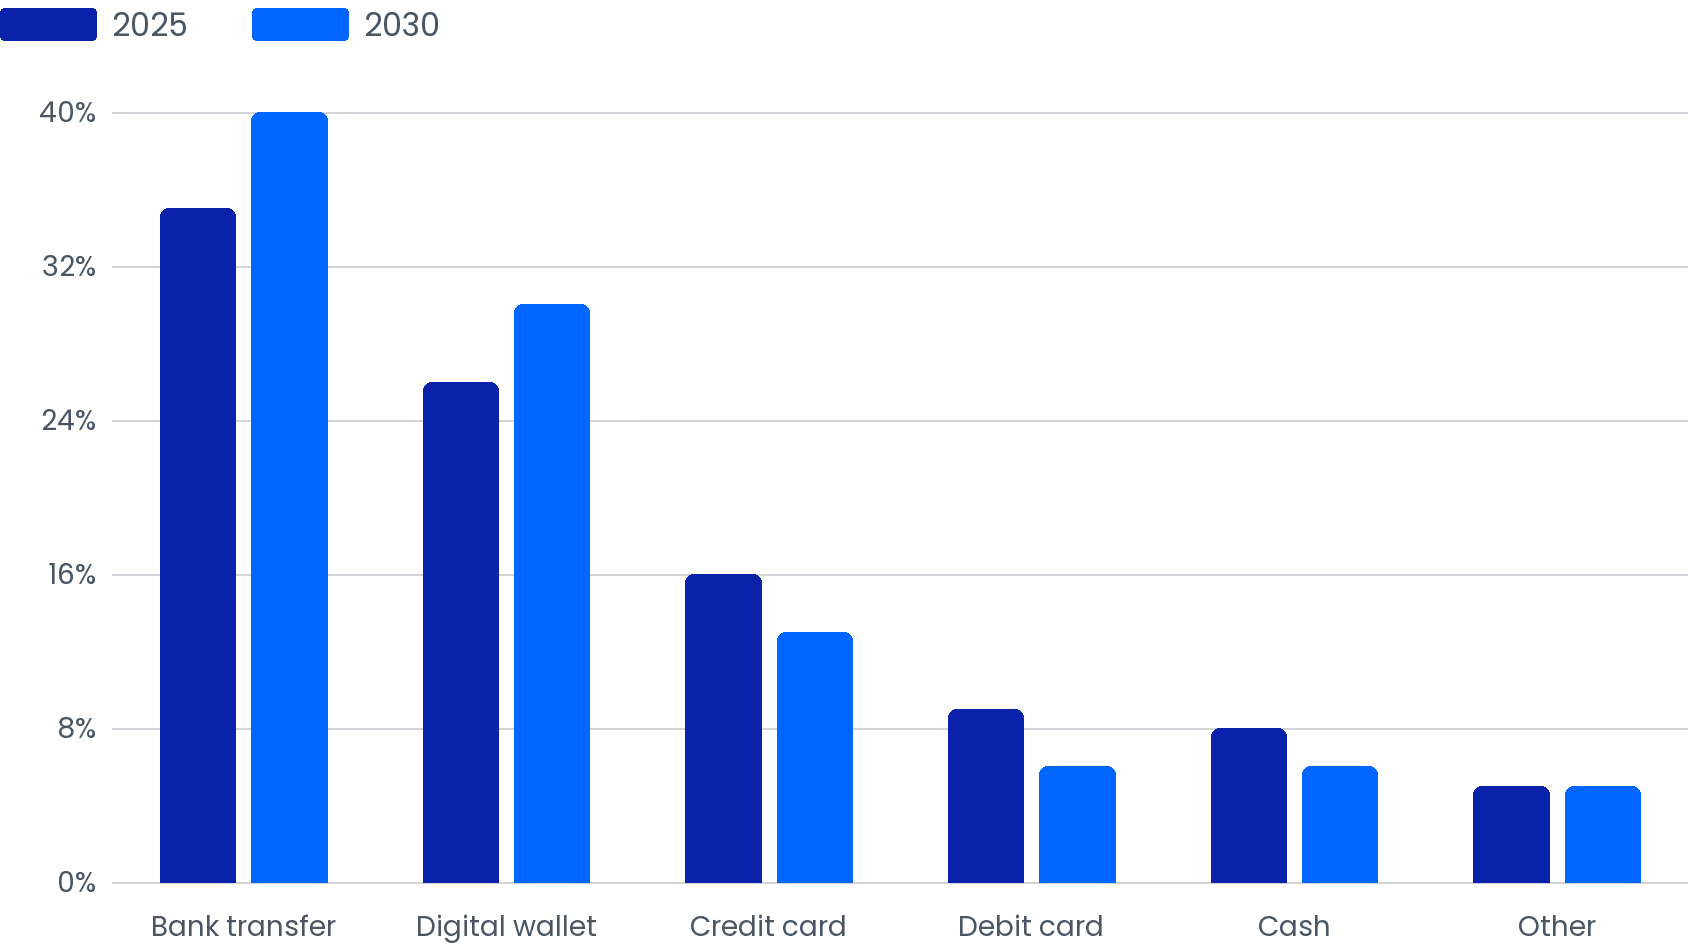
Bank transfers are projected to grow from 35% to 40% by 2030; digital wallets from 26% to 30%. Credit cards decline from 16% to 13%, debit cards from 9% to 6%, as mobile adoption accelerates. For merchants deciding how to structure payment method priority at checkout, the 2030 trajectory reinforces the importance of bank transfers for a Malaysia launch.
Malaysia payment methods: 2025 vs 2030 share %